A screen says “cheap,” but the business feels risky
It usually starts with a list that looks almost too clean: the company’s EV/EBITDA sits at the bottom of its peer group, the headline earnings are stable, and the chart even looks “washed out” enough to tempt a contrarian buy. Then the unease shows up. The product feels cyclical, customers seem concentrated, a plant expansion is rumored, or the balance sheet has that slightly tight look that makes refinancing feel like a calendar problem, not a strategy.
That’s the first warning: the screen is pricing something you can’t see in the multiple. The business can be “cheap” because it needs more cash put back in than peers, because the capital stack is doing more work than operations, or because obligations live off to the side in leases and working-capital swings. Before trusting the gap versus competitors, the question shifts from “why is it cheaper?” to “what risk is the multiple quietly carrying?”
Why EV/EBITDA seems like the perfect shortcut
In that moment, EV/EBITDA feels like the one number that should cut through the noise. Enterprise value pulls debt into the price, so a highly levered company doesn’t look “cheap” just because the equity is small. EBITDA strips out interest and taxes, so differences in financing and jurisdiction don’t dominate the comparison. And by adding back depreciation and amortization, it seems to neutralize accounting lives and old purchase-price allocations that can make operating profit look artificially low.
It’s also fast, which matters when the constraint is time: a watchlist of 40 names, a Monday morning earnings print, or a banker’s book with thin disclosures. The multiple looks like a rough “payback” on operating cash generation before capital structure. The trap is that it quietly assumes the cash generation is similarly durable across peers—especially once reinvestment demands show up.
The mismatch shows up when reinvestment isn’t equal
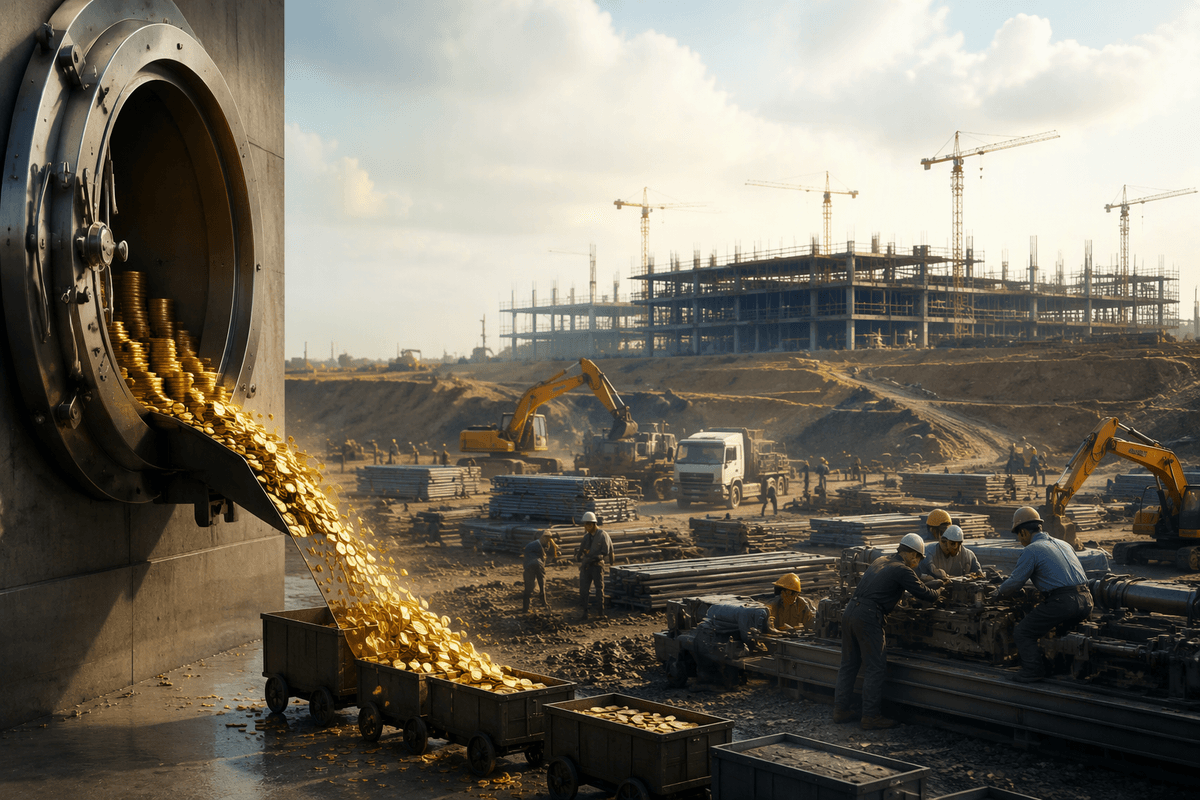
The multiple starts to bend the moment two “similar” companies need very different amounts of cash just to keep standing still. EBITDA treats a dollar of operating profit as equally valuable across peers, but the business that has to replace equipment, refresh stores, or rebuild software every year is effectively pre-spending part of that EBITDA. On a screen, it still looks cheap. In the bank account, it’s constantly handing the money back to suppliers and contractors.
This is where capital intensity turns into a hidden tax. One firm can run with modest maintenance capex and stable working capital, letting EBITDA convert into free cash flow with little drama. Another can post the same EBITDA margin while living on continuous reinvestment—higher maintenance capex, heavier inventory needs, or customer terms that soak up cash right when volumes rise. The constraint is timing: reinvestment is immediate, while the “earnings” benefit is gradual and uncertain. EV/EBITDA doesn’t price that gap unless the market is already punishing it.
Lease-heavy, debt-heavy, and the hidden obligation problem
The next snag is that “enterprise value includes debt” still isn’t the same as “enterprise value includes obligations.” Two businesses can report the same EV/EBITDA, but one is carrying a stack of fixed payments that behave like debt even if they don’t sit neatly in borrowings. Lease-heavy models do this in a quiet way: the stores, fleets, warehouses, and equipment come with contractual payments that have to be met in good quarters and bad. That turns a normal demand dip into a liquidity event faster than the multiple suggests.
Even when leases are brought onto the balance sheet, comparability can stay messy. One peer might have shorter lease terms, more variable rent, or easier exit options; another is effectively locked into long, fixed commitments. EBITDA doesn’t reflect that difference in flexibility, and EV can still understate how “senior” those payments feel alongside true debt maturities. The practical constraint is refinancing and renewal timing: if debt comes due the same year leases reprice higher, the “cheap” multiple can be pricing a calendar of obligations, not a bargain.
Accounting choices can inflate EBITDA without real gains
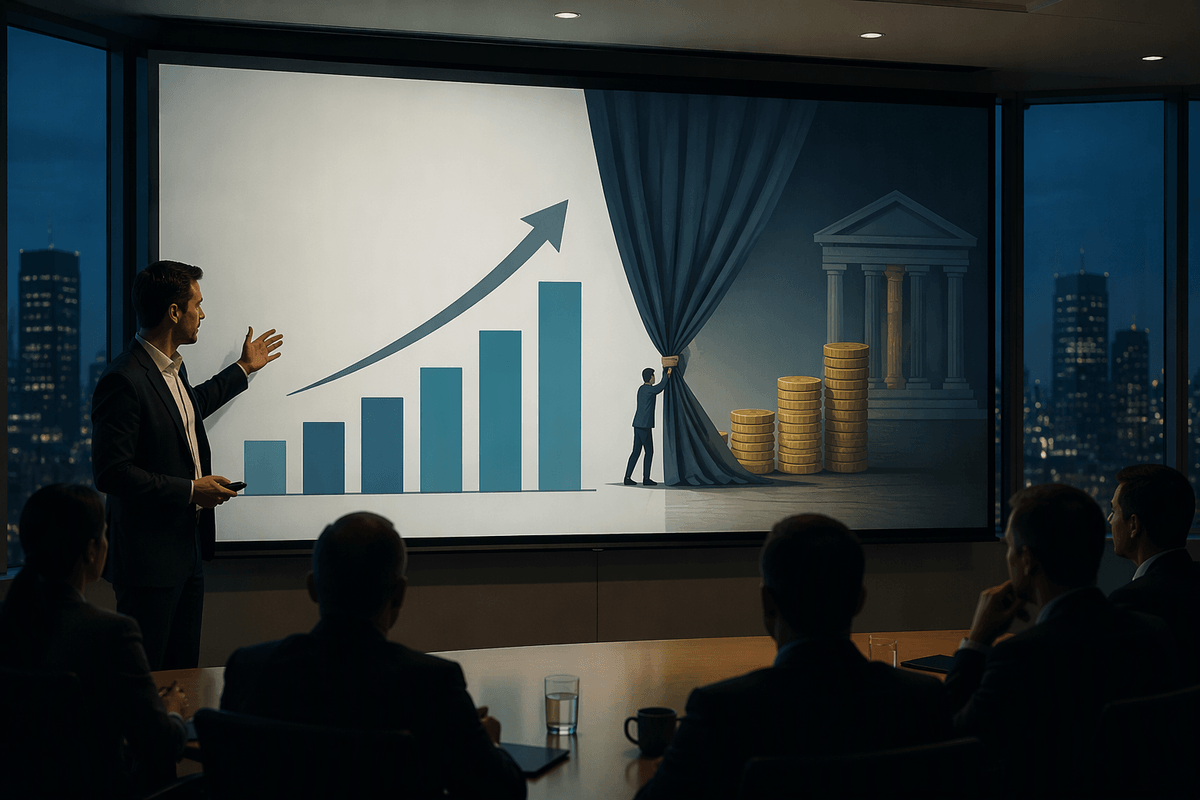
The next time EV/EBITDA looks unusually low, it’s worth checking whether EBITDA is being “helped” by choices that don’t change the economics. The common pattern is timing: costs that used to hit operating expense get pushed into capital spending or into acquisition accounting, which means they disappear from EBITDA even though the cash still leaves. A roll-up can show rising EBITDA simply because more of the spend is labeled integration, restructuring, or “one-time,” and the add-backs become part of the run-rate story.
Then there’s the quieter lift from capitalization. If a business starts capitalizing more software development, implementation, or even certain fulfillment and contract costs, current-period expenses fall and EBITDA rises, but the obligation returns later as amortization (which EBITDA ignores) and, more importantly, as repeat spending to keep the system current. The constraint is comparability across peers and across time: two companies can sell the same product with the same cash profile, yet the one with more aggressive capitalization will screen cheaper on EV/EBITDA while carrying a bigger “future expense” tucked inside the assets.
A quick repair kit before you trust the multiple
So before that low multiple gets to feel like a verdict, it helps to run a small set of checks that don’t require building a full model. First, put EBITDA on a tighter leash: back out recurring “adjusted” add-backs, normalize for unusually high or low working-capital years, and sanity-check margins against the company’s own history, not just peers. If the last twelve months look unusually clean, look for what was pulled forward, deferred, or capitalized.
Next, pair the multiple with reinvestment reality. A quick proxy is EV divided by EBIT (or EBITDA minus an estimate of maintenance capex) and then a glance at free cash flow conversion over a cycle. If EV/EBITDA says “cheap” but free cash flow is consistently thin, you’re probably looking at capital intensity, lease pressure, or cost timing—not a mispriced franchise.
Finally, stress the obligations calendar. Lay debt maturities next to lease commitments and ask a blunt question: if volumes dip for two quarters, does the company have room to breathe without refinancing at a bad moment? The multiple gets more trustworthy when the answer isn’t “it depends on the credit window.”
When to abandon EV/EBITDA and switch tools
After those quick repairs, sometimes the multiple still won’t behave. If free cash flow is the real bottleneck—steady EBITDA, chronically weak cash after maintenance spend—EV/EBITDA is no longer the right scoreboard. That’s when I stop arguing with the screen and switch to EV/free cash flow or price/free cash flow, even if the numbers look less “clean” quarter to quarter.
If leverage and fixed payments are the real risk—tight maturities, heavy leases, or refinancing sensitivity—I lean on credit-style views: net debt/EBITDA, interest coverage, and a simple liquidity runway. And if the business is in a reset—turnaround, heavy build-out, or acquisition churn—EV/sales with gross margin and unit economics often tells the truth sooner than “adjusted” EBITDA. The goal shifts from precise cheapness to avoiding the wrong kind of cheap.