Intro: Your “safe” bond flashes a downgrade alert
It usually starts as a routine account check: the bond fund in a workplace plan that’s been “the steady one” is down more than the last few rate moves would explain. Then a notice appears in the holdings list—rating watch, outlook negative, or an outright cut. Nothing about the coupon changed, and the maturity date is still the same, but the label that made it feel uncomplicated just shifted.
The frustrating part is timing. If the downgrade is real, waiting can mean you absorb a wider spread and thinner liquidity. If it’s just one agency moving first, selling now can lock in a dip that would have faded. Either way, the next price move often isn’t about your conviction—it’s about who’s allowed to hold the bond once it stops qualifying as “investment‑grade.”
What you assumed investment‑grade would protect you from
In a retail portfolio, “investment-grade” tends to get treated like a guardrail: the bond might wobble with rates, but it shouldn’t gap down on credit. That’s the first assumption that breaks. Ratings are opinions that adjust after fundamentals deteriorate, so the market can reprice the bond well before the label changes. The constraint shows up fast in a fund or workplace plan option: the daily NAV reflects that repricing whether or not you planned to take single-name credit risk.
The second assumption is that liquidity stays normal. Around a downgrade, bid-ask spreads can widen and trading can get intermittent, especially if the issuer is large enough to be widely held but suddenly “out of mandate.” That’s when price can move on flow, not news. The third assumption is that diversification inside an investment-grade fund eliminates the problem; it reduces default impact, but it doesn’t prevent concentrated selling in the same downgrade window. What matters next is how that repricing typically unfolds before, during, and after the cut.
How prices usually move around the downgrade window
By the time the downgrade headline hits a retail screen, the bond’s spread has often already been drifting wider for weeks or months. That’s the awkward part of the “window”: the market tends to price the probability of a cut before the agency makes it official, so the first leg down can feel like it came from nowhere. In a fund, that repricing shows up as a steady NAV leak that looks like rate pain, even when Treasury yields haven’t moved much.
Closer to the decision date, price action usually turns jumpier. Dealers quote less size, bid-ask spreads widen, and small trades can print at noticeably different levels. The actual downgrade day can be anticlimactic or sharp, depending on whether the cut was “fully priced,” but the constraint is liquidity: if you need to sell into that moment, the cost is often paid through a worse execution, not just a lower price.
After the cut, a second phase sometimes follows: forced sellers finish, crossover and high-yield buyers step in, and the bond can stabilize or even retrace a portion. It’s not a rule—just a common pattern that makes “wait or act” feel like a timing bet even when the goal is simply controlling downside.
When selling pressure comes from rules, not opinions
The part that catches people off guard is how quickly the holder base changes once the bond crosses the line. A lot of money isn’t deciding, it’s complying. If a bond falls below investment-grade, many investment-grade mutual funds, ETFs, separate accounts, and some workplace-plan sleeves are restricted by prospectus language, internal risk policy, or benchmark rules. That can translate into selling on a schedule, not selling at a “fair” price.
In practice, it shows up as a one-way tape even when the new information is already old. Index-tracking funds may need to remove the bond when it no longer qualifies, and “investment-grade only” managers may have limited discretion to hold a fallen angel through the transition. The constraint is timing: redemptions and rebalances happen on set dates, while liquidity is often worst in the same window. That mismatch can push the bond cheaper than fundamentals alone would suggest—temporarily—but it also means the drawdown can deepen before it gets any chance to mean-revert.
Find where you’re exposed in your own holdings
The next awkward step is realizing the downgrade doesn’t just sit in one “bond.” It shows up wherever that issuer is hiding in your stack: the core bond fund in a 401(k), the “intermediate” ETF in a brokerage account, the stable-looking corporate sleeve inside a target-date fund. The constraint is visibility—workplace plans often truncate holdings, and even in a brokerage it’s easy to miss that multiple funds share the same large issuers. Start by pulling the fund’s full holdings list and searching the issuer name, then add up exposure across accounts as a percent of your total portfolio, not just within the fund.
Then check what kind of exposure it is. An individual bond is a single line item with a maturity date; a fund position is exposure to flows and rules, and it can sell at the worst point in the window. Look for three practical flags: the share in the fund (is it a top-10 holding?), the credit bucket (how much is already BBB, where most fallen angels come from), and the mandate language (does it say “investment-grade only,” “up to 5% below,” or “may hold if downgraded”)? That tells you whether you’re facing credit risk alone, or credit risk plus forced-selling risk.
Choose a response that fits your downside limits
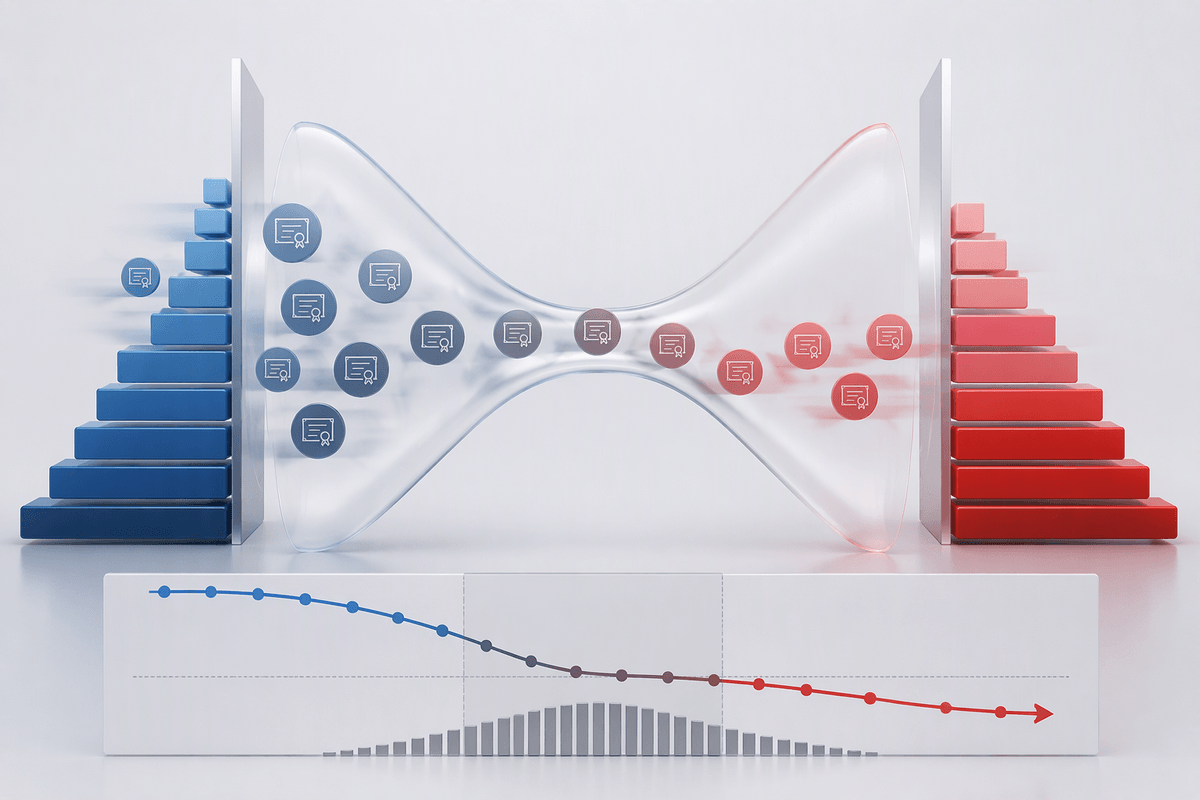
Once you know where the position sits, the decision becomes less philosophical and more about drawdown math. If this holding is supposed to be ballast, the cleanest move is often to reduce or exit and replace with higher-quality duration (Treasuries, agency MBS, or an investment-grade fund with tighter credit limits). The constraint is timing: selling into the downgrade window can mean paying a wider bid-ask spread, but waiting can mean living through a second leg lower if forced sellers haven’t finished.
If your downside limit can tolerate a credit event, you can treat it as a deliberate allocation: keep the position size small, diversify across issuers, and assume the price path will be uneven even if default risk stays low. A middle option is to trim to a pre-set cap and rebalance later, which turns “should I be right?” into “can I stay within plan?”
Conclusion: Revised thinking and a simple action checklist
After watching how a fallen angel actually trades, “investment-grade” feels less like protection and more like a set of rules that can change the holder base overnight. The surprise isn’t that credit risk exists; it’s that the ugliest price action can come from timing, liquidity, and mandate-driven selling—right when a retail holder is least able to control execution. That shifts the goal from predicting the next spread move to keeping the position inside a downside limit you can live with.
Simple checklist: (1) quantify issuer exposure across accounts, (2) read the fund mandate for below-IG flexibility, (3) decide a max % of portfolio you’ll risk in “maybe-BBB” credit, (4) pick a replacement bucket before you sell, (5) if you hold, set a size cap and a review date tied to the next rebalance window.