When Strong Growth Leaves Less Cash Behind
A company can report strong sales growth while ending the quarter with less cash than it started with. New orders may require inventory, hiring, shipping, or heavier customer support before the related receipts arrive. If suppliers allow longer payment terms, that gap can temporarily make growth self-funding. The same pattern can also appear when bills are being delayed because cash is tight.
That makes negative working capital an incomplete signal, not an automatic advantage. The judgment depends on timing and pressure: how quickly customers pay, when suppliers must be settled, whether growth is accelerating, and whether overdue obligations are building. Strong expansion can explain the cash strain, but it does not remove the need to test whether the model remains durable as conditions change.
The First Surprise: Profit Does Not Equal Liquidity
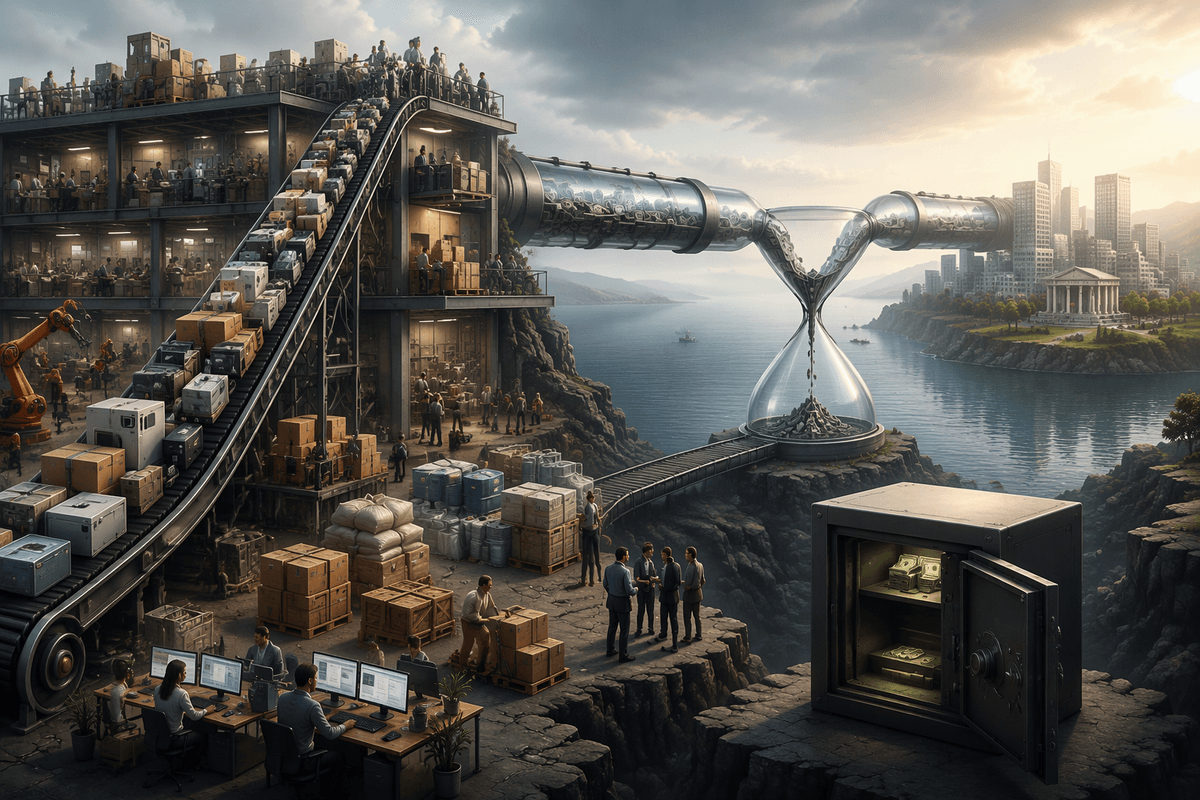
The surprise usually appears when earnings look healthy but the bank balance does not follow. Revenue can be recognized when a sale is made, while cash arrives weeks or months later. During that interval, the company still has to cover payroll, inventory, taxes, rent, and other operating costs. A profitable quarter can therefore increase the amount of cash tied up in receivables rather than cash available for use.
That gap becomes more important as growth speeds up. Each new sale may add accounting profit while requiring another advance payment to suppliers, another shipment, or more staff before collection. The timing can work in the company’s favor when customers pay promptly and suppliers remain flexible. It becomes a warning when receivables stretch, inventory accumulates, or payment delays spread across obligations. Profit confirms that the model may create value; it does not confirm that the company can meet its bills on time.
Follow the Cash Timing Before Judging the Model
The next step is to trace when cash enters and leaves rather than treating the working capital balance as a verdict. A retailer that collects customer payments at checkout and pays suppliers 45 days later may carry negative working capital for a sound reason: sales generate cash before replenishment bills are due. An online service business with annual upfront contracts can show a similar pattern, although the cash may need to support delivery over many months.
The test changes when the timing depends on pressure. Review customer payment trends alongside supplier terms, inventory purchases, payroll, taxes, and capital spending. If customers are paying more slowly while suppliers are being pushed beyond agreed dates, the apparent funding benefit is weakening. Rapid growth can also consume the advantage because each additional dollar of sales may require more inventory or service capacity before collections arrive. That creates a timing gap even when the reported working capital position still looks favorable.
A durable model usually shows repeatable collection behavior and supplier terms that reflect normal commercial relationships. A fragile one needs ever-faster growth, repeated extensions, or emergency borrowing to keep the cycle moving. The balance matters, but the sequence of cash events reveals whether it is earned or merely deferred.
A Supplier-Funded Model Has Limits
Supplier credit can make a growing business appear more liquid than it would be on its own. Longer payment terms leave cash available after a sale, allowing the company to fund inventory, payroll, or expansion with money that technically belongs to vendors. That benefit has a ceiling. Suppliers may shorten terms, require deposits, reduce credit limits, or stop shipping when balances rise faster than confidence.
The risk is greater when the company has little negotiating power or depends on a small group of vendors. A supplier-funded model is healthier when terms are stable, purchases match confirmed demand, and obligations are paid within the normal cycle. It is more concerning when management needs repeated extensions, selectively pays vendors, or increases purchasing simply to support sales that have not yet produced cash. Those actions can preserve reported growth while narrowing room for error.
Stress often appears before a formal liquidity crisis: discounts disappear, late fees increase, and suppliers demand cash on delivery. At that point, negative working capital is no longer evidence of efficient timing alone. It may reflect financing that can be withdrawn precisely when slower growth makes replacement funding hardest to obtain.
Growth Can Hide the Moment Liquidity Turns
Growth can postpone the warning because rising sales keep new cash entering the cycle. A business may use collections from recent orders to cover older supplier balances, while each new round of expansion adds inventory, staffing, or delivery costs. The reported working capital position can still look favorable even as the margin for timing errors gets smaller.
The turning point often appears when growth slows, customers delay payment, or suppliers tighten terms. Cash inflows then lose momentum, but the obligations created during expansion remain. Watch whether operating cash flow weakens despite higher revenue, whether receivables and inventory grow faster than sales, and whether borrowing increases to fund routine needs. A company that can reduce purchasing, preserve supplier confidence, and convert sales into cash has room to adjust. One that needs continued growth to settle yesterday’s commitments is carrying a different risk. The concern is not that growth consumes cash; it is that growth may conceal how little liquidity remains once the cycle stops accelerating.
The Evidence That Separates Advantage From Distress
The distinction becomes clearer when the same measures are tracked across several periods rather than judged from one balance sheet. A genuine operating advantage usually combines steady or improving cash conversion, customer payments that follow agreed terms, and supplier balances settled without unusual extensions. Growth may still consume cash, but the business can explain the timing and adjust purchasing or hiring when demand changes.
Distress leaves a different trail. Receivables age beyond normal terms, inventory rises ahead of sales, and accounts payable increase faster than operating activity. Management may describe this as temporary growth funding, yet repeated late payments, emergency borrowing, tax arrears, or supplier demands for deposits point to pressure rather than efficiency. The constraint is practical: once vendors reduce credit, the company must replace that funding quickly or cut operations.
The strongest evidence is behavior under slower growth. If cash improves when expansion moderates, the model may be working. If liquidity worsens because old obligations remain while new sales fade, negative working capital was masking dependence on continued acceleration.
A Better Verdict Depends on Durability
The better verdict comes from durability, not from the direction of working capital alone. A healthy model should keep converting sales into cash under ordinary pressure: slower growth, stable or slightly weaker customer payments, and normal supplier terms. It should also leave management choices beyond borrowing more or delaying bills. That resilience matters because favorable timing can disappear quickly when demand changes.
Negative working capital is therefore an advantage only when its funding sources remain dependable and commercially justified. When cash conversion weakens, obligations stretch, and growth becomes necessary to keep the cycle alive, the same figure carries a different meaning. The conclusion should remain conditional: operating strength is credible when the model survives slower growth without financial strain.